
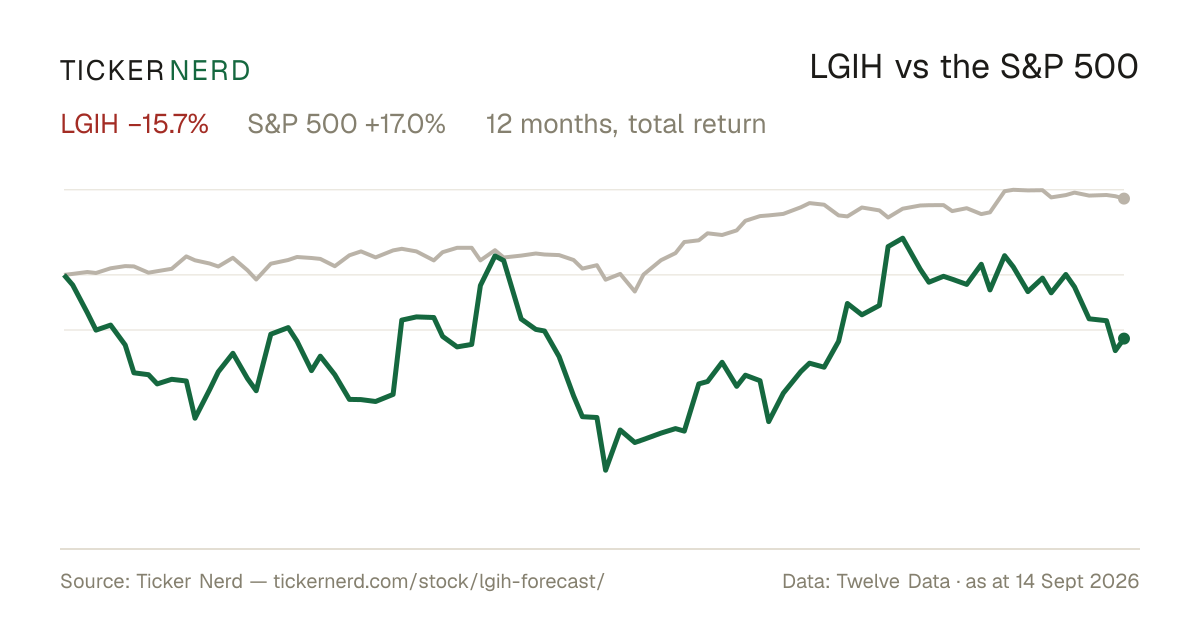
LGI Homes Will Likely Continue Underperforming The Market
Seeking Alpha · 20 Oct 2026negative
Seeking Alpha says LGI Homes faces continued pressure from high leverage, a premium valuation, and declining profitability despite revenue growth. It cites rising rates, inflation, weaker consumer demand, higher cancellations, slower order growth, and $1.52 billion in net debt with a 9.38 net leverage ratio.
Why it matters — These concerns highlight risks to LGIH’s profitability and demand, alongside leverage well above peers.