
Miller Industries Isn't Cheap Enough To Justify An Upgrade
Seeking Alpha · 30 Aug 2026negative
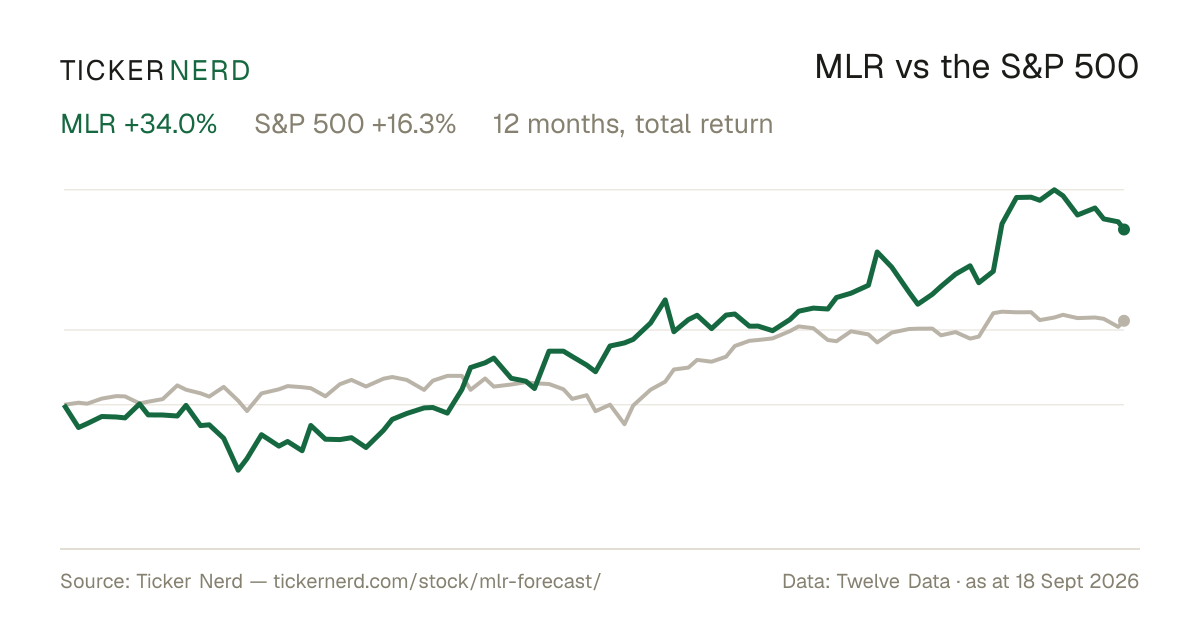
Miller Industries' shares rose 17.6%, outperforming the S&P 500, helped by strong revenue growth and the Omars acquisition. However, net income and core cash flow declined amid higher tariffs and lower-margin chassis sales, and management guides to flat EPS and cash flow versus last year despite FY revenue of $850–$900 million.
Why it matters — For MLR watchers, the item notes that despite solid revenue gains, profitability and cash flow are under pressure and current valuation does not justify an upgrade.