MarketBeat · 28 Sept 2026neutral
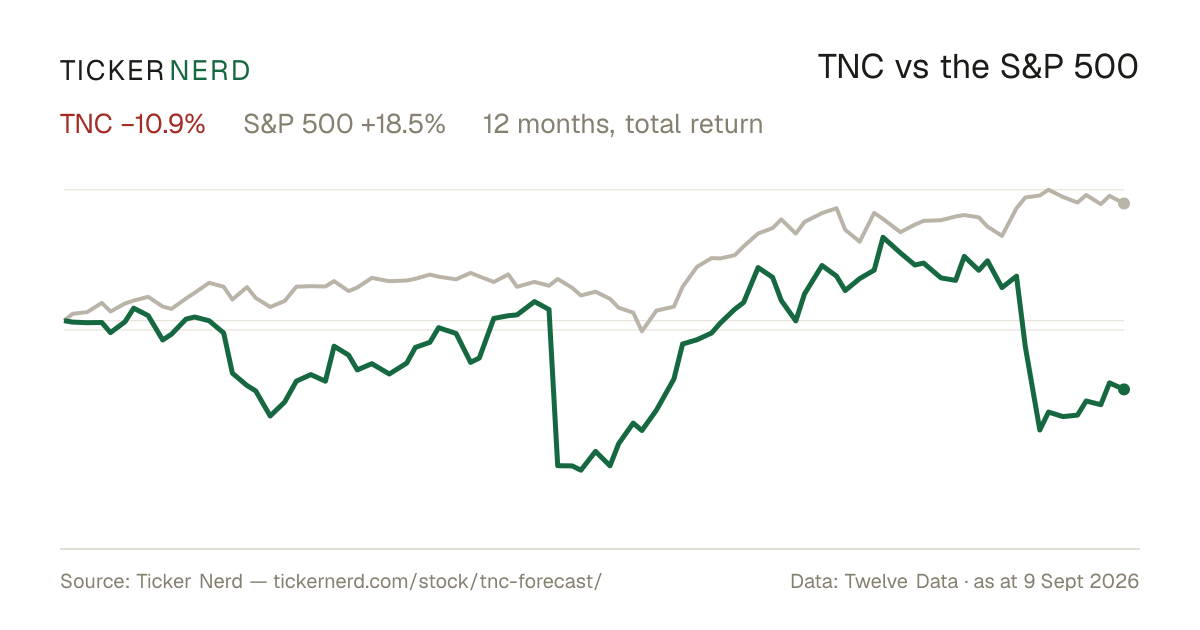
Tennant CEO Dave Huml stated the floor-cleaning equipment maker is pursuing growth through automation, robotics, product innovation, and targeted acquisitions, while continuing to recover from a North American ERP implementation that disrupted operations in late 2025.
Why it matters — TNC watchers would care because the company's strategic growth focus and ongoing ERP recovery will shape its near-term operational performance.
Seeking Alpha · 24 Sept 2026positive
Tennant Company faces short-term profitability setbacks due to supply chain and ERP issues, with revenue growing modestly but net income and EBITDA declining sharply, prompting lower profit guidance. Despite this, the company maintains a soft 'buy' rating based on relative valuation and growth prospects, with management focused on growing robotics revenue from $85M to $250M by 2028.
Why it matters — A TNC watcher would care because the report highlights near-term profit pressure alongside a strategic push into robotics and automation that management expects to more than triple by 2028.
Seeking Alpha · 18 Sept 2026negative
Seeking Alpha ranks the Dividend Kings—companies with 50+ years of increasing dividends—using its 9F Quality Scores. ADP is highlighted as the best total-return candidate, described as undervalued, high-quality, and offering strong projected dividend growth.
Why it matters — The article's absence of Tennant Co. from the highlighted quality standouts carries neutral-to-unfavorable implications for how a TNC watcher might perceive its relative standing among Dividend Kings.
Seeking Alpha · 24 Aug 2026positive
Seeking Alpha reports that Dividend Kings are outperforming the S&P 500 year-to-date with a 14.98% total return versus SPY's 12.89%. Thirty Dividend Kings are beating SPY, with 25 appearing potentially undervalued and offering at least 10% annualized return potential, while dividend growth accelerated to an average rate of 4.12% with several notable increases announced.
Why it matters — As a potential Dividend King, TNC watchers would care about this update on the group's relative outperformance and accelerating dividend growth, which reflects on the broader dividend-growth landscape the company is part of.
MarketBeat · 9 Aug 2026negative
Tennant reported second-quarter 2026 sales growth and stronger order activity, but profitability fell short of management's expectations due to ERP-related operating inefficiencies, North American parts shortages, inflationary costs, and competitive pricing pressure in Europe.
Why it matters — TNC watchers would care because the top-line growth and order momentum were offset by profitability challenges tied to operational, supply-chain, and pricing headwinds.