
The Pricing Power Prescription: Unlocking Universal Health Services' Hidden Fair Value
Seeking Alpha · 27 Aug 2026positive
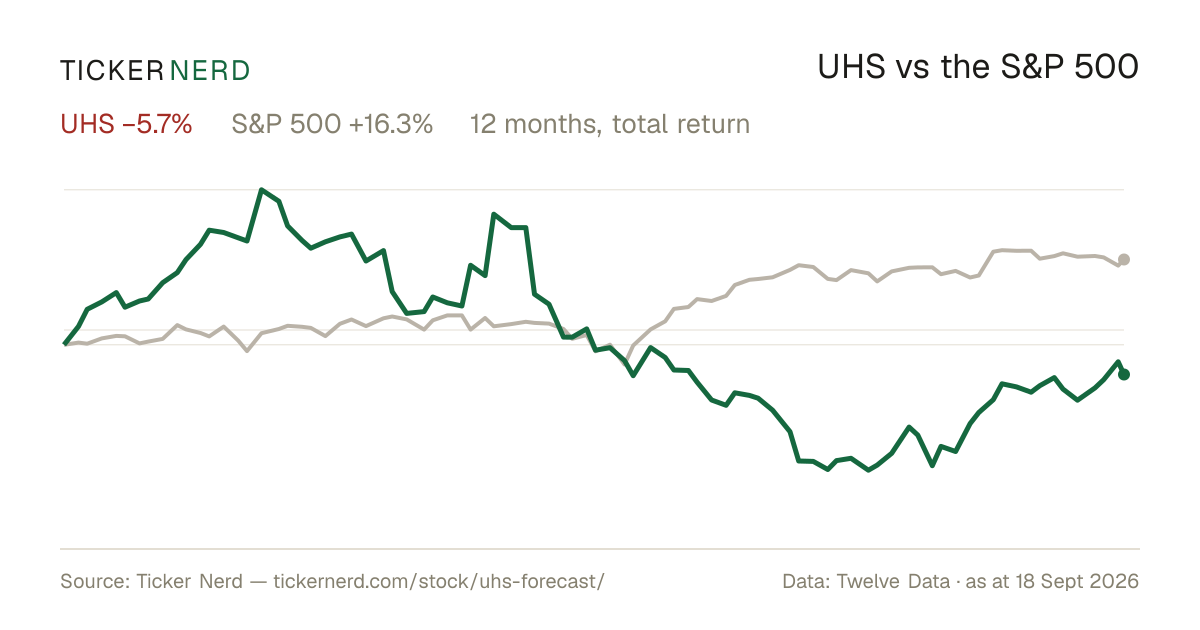
A Seeking Alpha analysis argues Universal Health Services is deeply undervalued at 7.4x 2026E NTM earnings, citing robust free cash flow, pricing power, structural tailwinds in behavioral health, a 15.5% ROIIC, and disciplined share buybacks. The piece projects a 12.1% FCFE-per-share CAGR through 2030E and sets a base-case fair value of $280.99.
Why it matters — A UHS watcher would care because the analysis highlights the company's valuation, cash-flow generation, and behavioral health growth drivers that could influence its perceived fair value.