
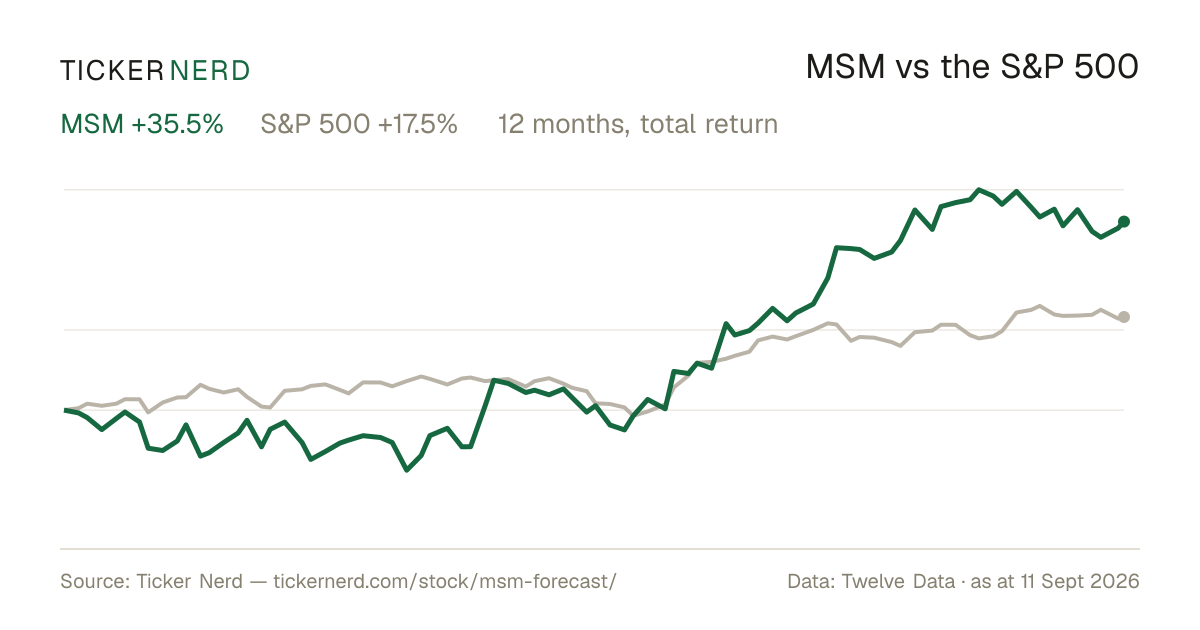
MSC Industrial Direct: Why The Upside Is Insufficient Given The Price
Seeking Alpha · 2 Oct 2026negative
A Seeking Alpha analysis discusses MSC Industrial Direct's recent operational turnaround, citing 7.8% revenue growth and 32% adjusted EPS growth in 3Q26, while noting cyclicality and margin risks. The article concludes that MSM's upside is insufficient given its price, as peer comparison shows it less qualitative than Fastenal or Grainger with lower long-term growth and margins.
Why it matters — MSM watchers would care because the analysis argues the stock's valuation offers insufficient upside relative to its risks and weaker positioning against key industrial distribution peers.