
SFL Corporation: High Yield Protected By Strong Backlog, But Upside Is Priced In
Seeking Alpha · 20 Oct 2026negative
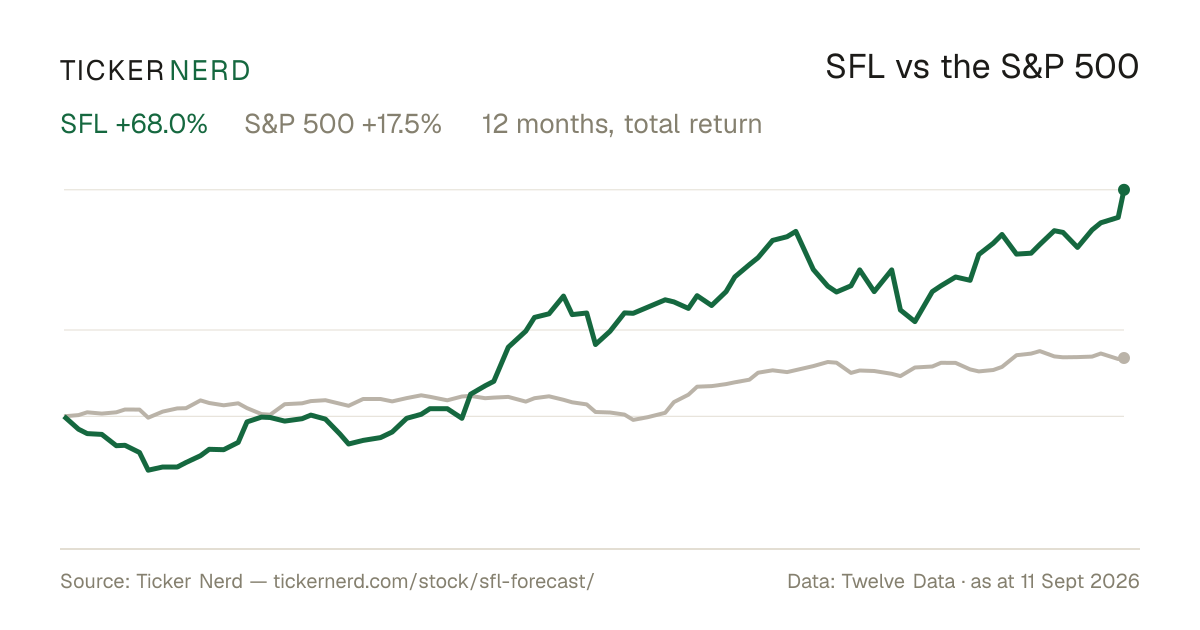
Seeking Alpha says SFL has improved its counterparty risk profile and could release capital by selling oil tankers. The article notes that its 7.0% dividend yield may not cover new-vessel financing costs and reinvestment needs, and gives a Hold view.
Why it matters — SFL watchers may weigh the improved risk profile and potential tanker-sale proceeds against the article’s concerns about financing costs and reinvestment needs.