
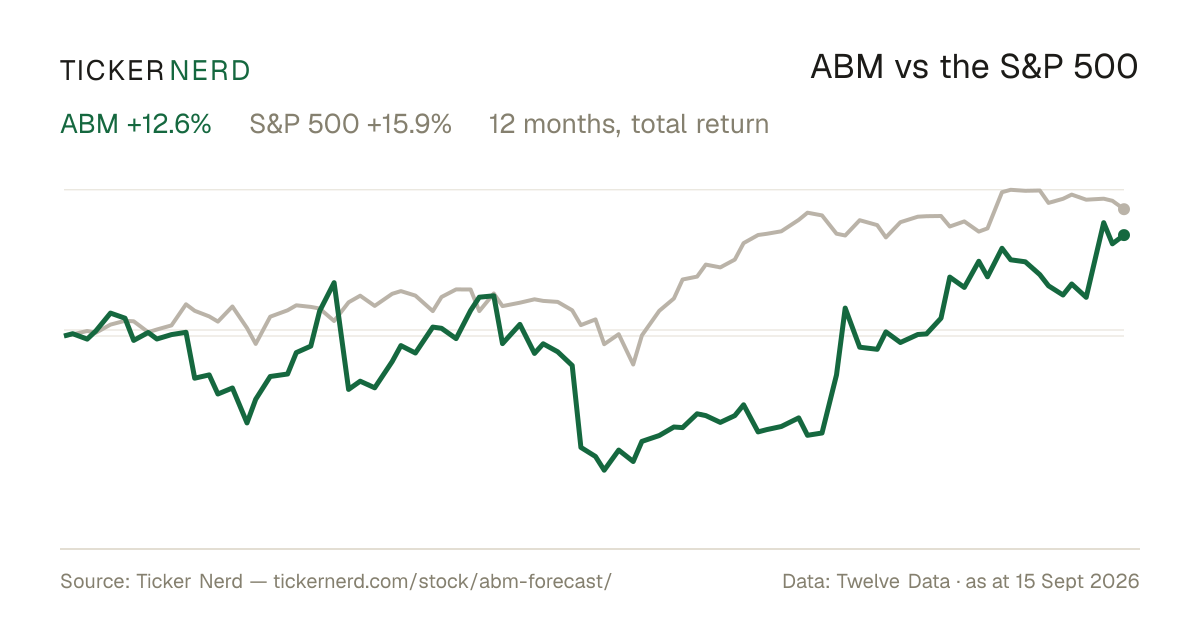
ABM Industries: Boring Business, High-Tech Polish
Seeking Alpha reports that ABM Industries remains attractively valued at around 11x forward earnings, with healthy mid-single-digit revenue growth driven by Data Centers, Semiconductors, and M&A—areas now making up 11% of revenue. The article notes margin-expansion opportunities from operational efficiencies and technology adoption, while flagging low EBITDA margins as an industry challenge. why_it_matters: ABM watchers would care because the company's growth is increasingly concentrated in higher-tech segments, and the analysis highlights both margin-expansion potential and the competitive pricing pressures affecting its profitability outlook. sentiment: positive
Why it matters — ABM watchers would care because the article underscores the company's attractive valuation and growing contribution from data center, semiconductor, and M&A-driven segments, while also flagging low EBITDA margins and competitive pricing as ongoing profitability challenges.