
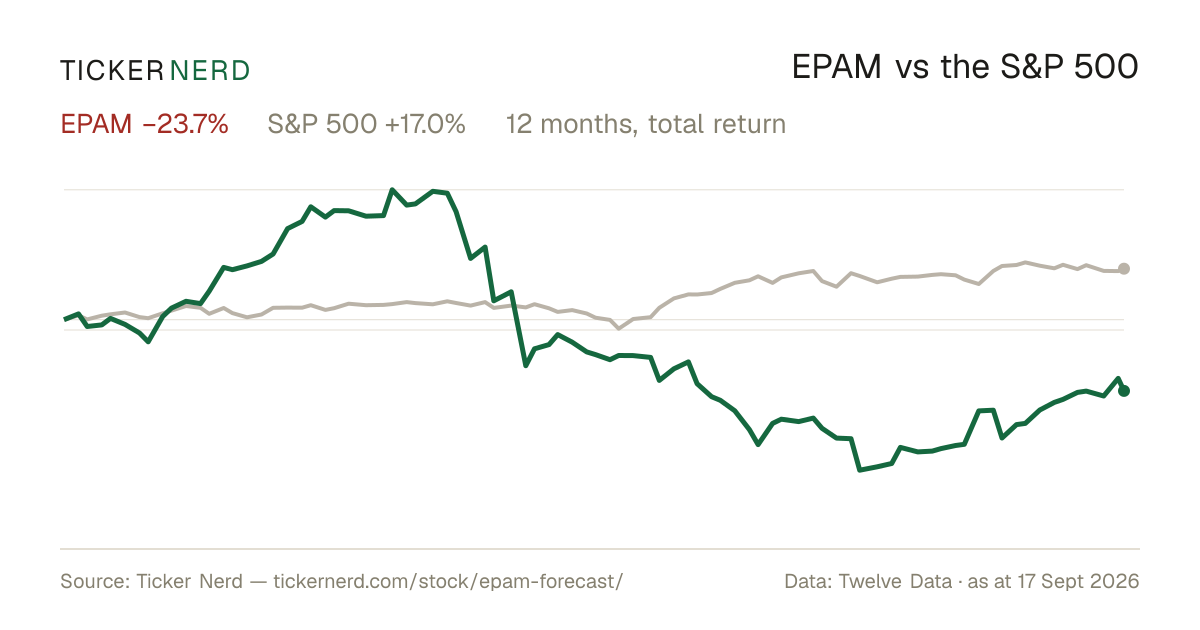
EPAM Systems: Strong Buybacks And A Low Valuation Offer Upside
Seeking Alpha · 12 Oct 2026positive
A Seeking Alpha commentary describes EPAM’s transition as AI disrupts traditional software services, noting that AI-related revenue accounted for 11% of Q2 2026 sales but largely replaced legacy work. It also highlights share repurchases, a strong net cash position, and valuation multiples of 7x EV/EBITDA and 11x P/CF.
Why it matters — EPAM watchers may weigh AI’s limited near-term growth contribution against the company’s buybacks, cash position, and cited valuation.