
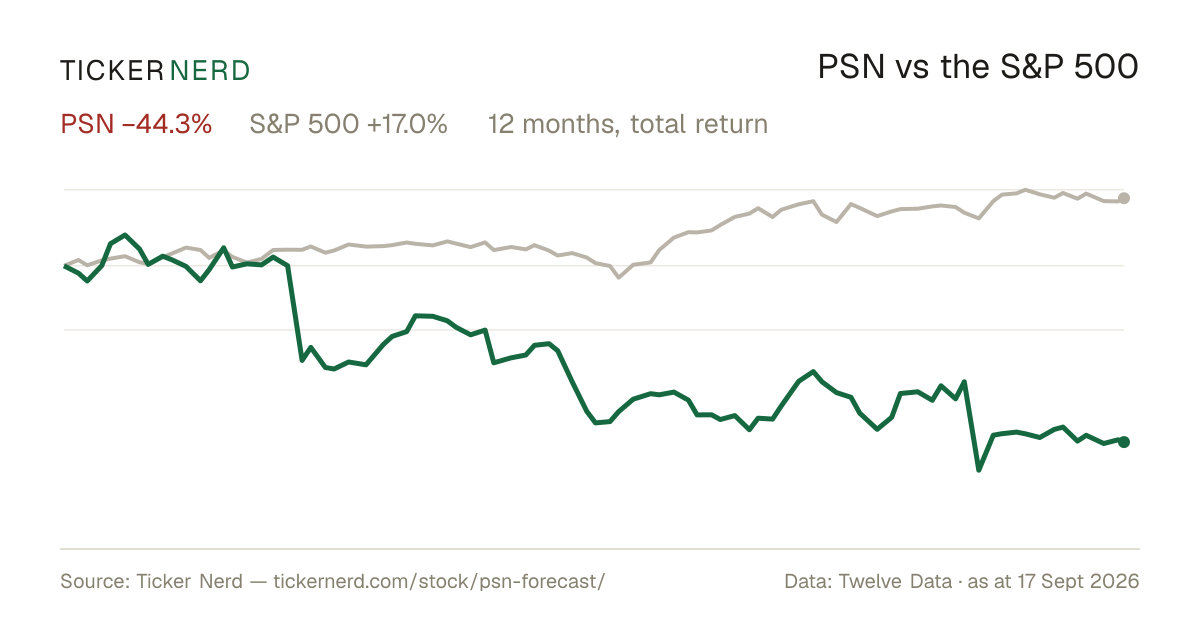
Parsons Has Improved, But The Rebound Leaves Little Room For Error
Seeking Alpha · 31 Oct 2026negative
Parsons reported record Q3 adjusted margins of 10.2% and revenue of $1.7 billion, but growth remained modest and project risks persisted, including unresolved contract exits. The article says the shares are near its $51.09 base case and that recent momentum does not offset limited valuation upside.
Why it matters — PSN watchers may weigh improved profitability against tepid growth, contract risks, and the article’s view that valuation leaves little room for upside.