HCCHCCBasic Materials · Coking Coal

HCC Stock Forecast: Warrior Met Coal, Inc. Price Predictions for 2026-2027

Last close, 8 Oct 2026
$90
+0.26% on the day

The 7 Wall Street analysts covering Warrior Met Coal, Inc. hold a median 12-month price target of $105 — +16.9% from the last close. Ticker Nerd's systematic factor model, run across ~4,600 US stocks, ranks it 86 of 100 as at 8 Oct 2026 — inside the top quartile. Here, the model and the Street point the same way.

Market cap
$4.9B
Ticker Nerd rank
86 / 100
Median analyst target
$105
Analysts covering
7
Revenue$509.7M+71.3% y/y
Operating income$94.5M
Net income$87.4M
Free cash flow$103.4M
Quarterly, 8 quarters to 30 June 2026 · latest quarter's figure shown
Total return, dividends reinvested
1W
+0.8%
1M
−14.9%
YTD
+2.1%
1Y
+38.9%
From 52W high
−18.5%
From 52W low
+44.5%
$62
$110
52-week range, adjusted closes · the dot is the last close
Ticker Nerd rank

HCC stock analysis: one number for the whole business

Consensus tells you what everyone already believes. The model scores Warrior Met Coal, Inc. on its factor families — the same systematic rank behind the Ticker Nerd portfolio.

Where the model ranks itAs at 8 Oct 2026
86 / 100

Percentile across ~4,600 US stocks on Ticker Nerd’s systematic factor model. Higher is better. How the model is built and tested

Growth
96
Momentum
86
Value
85
Volatility
80
Quality
79
Revisions
72
Issuance
45
Accruals
29
Size
24

Growth (96): Sales and profits are climbing, and climbing faster than before.

Accruals (29): A large share of reported profit has not shown up as cash, or the balance sheet is expanding quickly — both tend to unwind.

Size (24): Larger than most of the companies we track — more scrutinised, less often mispriced.

Built and run by Aslam Ghouse, an ex-Goldman Sachs quant trader with fourteen years in markets.

Wall Street

HCC stock forecast 2026-2027: analyst price targets & predictions

The bullish and bearish analyst opinions on HCC, reported as data — targets and ratings, the market's view beside the model's.

Share price and the analyst range, 12 monthsAdjusted close, US dollars
$60$80$100$120Jan 26Apr 26Jul 26Oct 26HCCHigh $125Median $105Low $98

Price targets and ratings are third-party analyst estimates, reported here as data. They are not Ticker Nerd forecasts, and they are frequently wrong.

Data provided by Twelve Data

What Wall Street says7 analysts
4 Buy3 Hold0 Sell
Low $98Median $105High $125

The green dot is the last close — the median target sits +16.9% from it.

Recent analyst actionsNewest first

Of the 20 most recent actions, 1 moved their price target up and 2 moved it down.

DateFirmActionRatingTarget
16 Sept 2026RBC CapitalMaintainsSector Perform$90 → $110
6 Aug 2026UBSMaintainsBuy$100 → $98
6 Aug 2026UBSMaintainsBuy—
30 June 2026UBSMaintainsBuy$102 → $100
30 June 2026UBSMaintainsBuy—
10 June 2026B. Riley SecuritiesMaintainsBuy—
1 May 2026UBSMaintainsBuy—
27 Mar 2026UBSMaintainsBuy—
18 Mar 2026CitigroupMaintainsBuy—
12 Mar 2026UBSMaintainsBuy—
13 Feb 2026B. Riley SecuritiesMaintainsBuy—
29 Jan 2026UBSUpgradeBuy—
20 Jan 2026JefferiesMaintainsBuy—
12 Dec 2025UBSMaintainsNeutral—
24 Nov 2025UBSMaintainsNeutral—
6 Nov 2025BMO CapitalMaintainsMarket Perform—
6 Nov 2025UBSMaintainsNeutral—
8 Oct 2025UBSMaintainsNeutral—
25 Sept 2025Texas Capital SecuritiesInitiatesBuy—
20 Aug 2025UBSMaintainsNeutral—

Price targets and ratings are third-party analyst estimates, reported here as data. They are not Ticker Nerd forecasts, and they are frequently wrong.

Market Radar

This page is one stock. Monday covers all of them.

Computed off the Friday close and sent before the US open.

Market Radar reports the week’s largest rank changes across roughly 4,600 US stocks, the factor behind each one, and where the market went. HCC appears on the weeks it earns a place.

Free, every Monday. Unsubscribe any time.

Performance

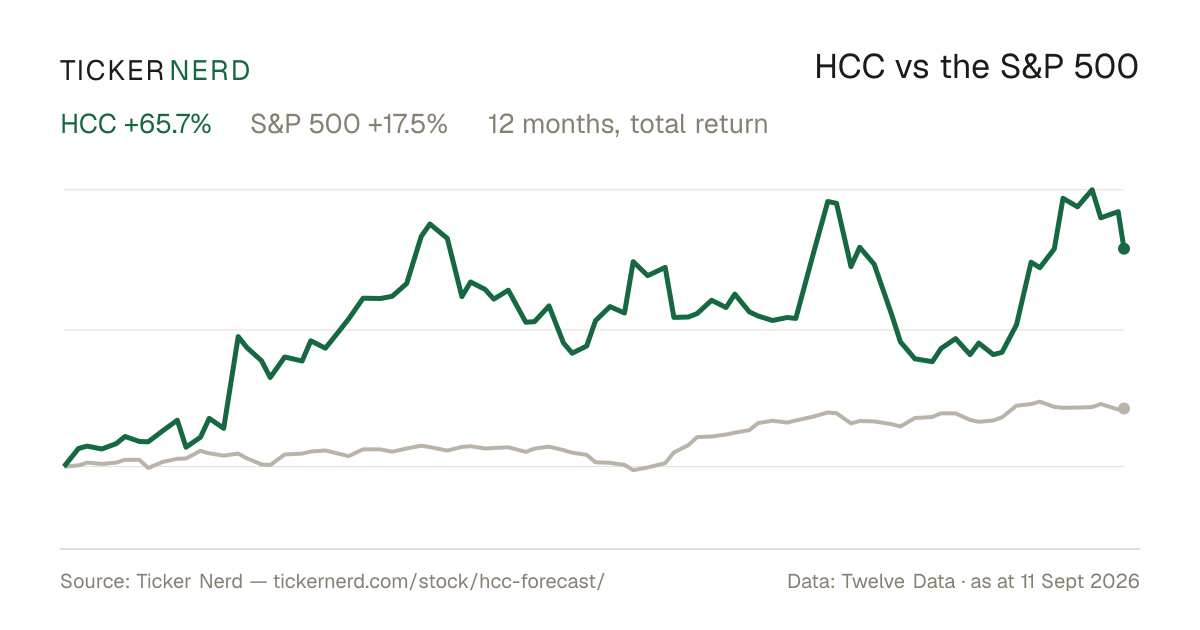
HCC vs the S&P 500

Both lines are total return — dividends reinvested — so the comparison is honest on both sides.

Over the twelve months to 8 Oct 2026, Warrior Met Coal, Inc. returned +38.9% against +16.2% for the S&P 500, dividends included.

HCC vs S&P 500, last 12 monthsTotal return, rebased to 100
100120140160Jan 26Apr 26Jul 26Oct 26HCCS&P 500

Download this chart as an image — free to reuse; link this page as the source.

Data provided by Twelve Data

Estimates

HCC analyst estimate revisions

Not the forecast itself — the direction analysts are revising it. Revision direction is one of the model's factor families.

Which way the estimates are movingNext fiscal year
EPS revision, 90 days
−6.4%
Analysts raising
1
Analysts cutting
4
Fundamentals

Warrior Met Coal, Inc. (HCC) financial data

A margin means little on its own. Each bar marks where the figure sits across the whole US universe we score.

Valuation
Trailing P/E
22.2×

Cheaper than 33% of US stocks

Price / sales
2.9×

Cheaper than 42% of US stocks

Price / book
2.1×

Cheaper than 42% of US stocks

EV / EBITDA
10.8×

Cheaper than 35% of US stocks

Growth & margins
Revenue growth (YoY)
71.3%

Higher than 90% of US stocks

Earnings growth (YoY)
1459.6%

Higher than 98% of US stocks

Gross margin
20.5%

Higher than 21% of US stocks

Operating margin
18.5%

Higher than 77% of US stocks

Net margin
13.0%

Higher than 75% of US stocks

Returns & dividend
Return on equity
10.0%

Higher than 63% of US stocks

Return on assets
5.2%

Higher than 77% of US stocks

Dividend yield
0.3%

Higher than 64% of US dividend payers

Bars mark the percentile across the ~4,600 US stocks Ticker Nerd covers, among those reporting the figure.

Key statistics

Warrior Met Coal, Inc. (HCC) statistics: revenue, profit & scale

The headline figures, each with its date. Every row carries its own link — cite it straight from here.

  • Warrior Met Coal, Inc. has a market value of $4.9B and an enterprise value of $4.8B.

  • Revenue in the twelve months to 30 June 2026: $1.7B. The latest quarter grew 71.3% year on year.

  • Net income over the same four quarters: $219.3M, a 13.0% net margin.

  • Diluted earnings per share, trailing twelve months: $4.16.

  • Free cash flow in the twelve months to 30 June 2026: $6.1M.

  • Warrior Met Coal, Inc. spent $17.4M on dividends in the twelve months to 30 June 2026.

  • Shares outstanding: 52.8M.

  • Trailing P/E: 22.2×; forward P/E: 13.3× — the forward figure prices analyst consensus estimates, not reported earnings.

  • Forward dividend yield: 0.35%, paying out 8% of earnings.

  • Warrior Met Coal, Inc. employs 1,485 people — $1.1M of revenue per employee.

Statement figures: company filings via Twelve Data, four quarters to 30 June 2026 · market figures as at 7 Oct 2026

Data provided by Twelve Data

Peers

HCC vs competitors

The nearest names by industry and size, scored by the same model — like for like.

Its peer group, ranked by the same modelCoking Coal
CompanyMarket capTKN rank
HCCWarrior Met Coal, Inc.$4.9B
86
AMRAlpha Metallurgical Resources, Inc.$2.2B
68
SXCSunCoke Energy, Inc.$825.5M
89
METCRamaco Resources, Inc.$499.5M
7
USARUSA Rare Earth, Inc.*$4.7B
10
CECelanese Corp.*$4.9B
61
PRMPerimeter Solutions, Inc.*$4.5B
22

* Nearest Basic Materials names by size — few coking coal companies of this scale trade in the US universe.

Look up any of the roughly 4,600 stocks we score.

The rank is the raw material. Whether the rules would actually own Warrior Met Coal, Inc. — and when they’d sell — is the membership. See the Ticker Nerd 20 →

News

Latest HCC news & analysis

Warrior Met Coal: A Volume Story Still Priced Like A Coal Price Bet

Seeking Alpha · 27 Sept 2026positive

Warrior Met Coal is increasingly driving earnings growth through volume and cost reductions rather than coking coal price leverage. The Blue Creek Mine's early ramp added a second product line, helping Q2 sales reach a record 3.7 million short tons and lowering unit costs to $92.53 per ton, which compresses forward multiples and offers greater visibility than price-driven peers.

Why it matters — HCC watchers would care because the company's shift toward contracted volume growth and lower unit costs provides more predictable earnings and valuation support than peers reliant on volatile coal prices.

Warren Buffett's Succession Triggers Search for His Spiritual Successors

24/7 Wall Street · 21 Sept 2026neutral

The article examines Warren Buffett's reduced role at Berkshire Hathaway, prompting a search for public companies that most closely follow his investment playbook. It raises the question of how closely any company can match the principles he used at Berkshire.

Why it matters — A HCC watcher would care because the piece evaluates public companies against Berkshire-style investment principles, placing firms like HCC within broader scrutiny of shareholder-value-oriented management.

Top 3 Materials Stocks That Could Sink Your Portfolio This Month

Benzinga · 1 Sept 2026negative

As of Sept. 1, 2026, Benzinga flagged three materials-sector stocks that could be flashing a warning to investors who prioritize momentum in their trading decisions. The piece names Warrior Met Coal among materials stocks that could risk portfolio performance this month.

Why it matters — HCC watchers may care because the item signals potential caution around the stock's momentum and performance in the near term.

Warrior Met Coal CEO Sells 50,000 Shares for $5.5 Million

The Motley Fool · 27 Aug 2026neutral

Warrior Met Coal CEO Walter J. Scheller sold 50,000 shares for $5.5 million on August 24, 2026. The sale represented 16% of the equity he held prior to the disposal.

Why it matters — A CEO insider sale of this size could be noted by HCC watchers as a potential signal regarding leadership's view of the company's stock.

Warrior Met Coal Q2 Earnings Call Highlights

MarketBeat · 8 Aug 2026positive

Warrior Met Coal reported sharply higher second-quarter earnings and cash generation, driven by contributions from its Blue Creek mine, and management raised its full-year sales and production outlook.

Why it matters — The increased sales volumes and lower-cost production from the Blue Creek mine, along with the upwardly revised full-year guidance, signal improved operational performance and growth potential for the company.

FAQ

Frequently asked questions about HCC stock

What is the HCC stock price forecast for 2026-2027?

The 7 Wall Street analysts covering Warrior Met Coal, Inc. have a median 12-month price target of $105, with estimates ranging from $98 to $125. These are third-party analyst estimates, not Ticker Nerd forecasts, and they are frequently wrong.

Is HCC stock a buy right now?

Of the 7 analysts covering Warrior Met Coal, Inc., 4 rate it a Buy, 3 a Hold and 0 a Sell. Ticker Nerd's systematic factor model ranks Warrior Met Coal, Inc. 86 out of 100 across roughly 4,600 US stocks as at 8 Oct 2026. None of this is personal advice — it does not consider your circumstances.

How does Ticker Nerd's model rank HCC?

As at 8 Oct 2026, Warrior Met Coal, Inc. ranks 86 out of 100 on Ticker Nerd's systematic factor model — a percentile across roughly 4,600 US stocks, built from its factor families. Its strongest factor family is Growth (96 of 100).

Will HCC stock go up?

No one can know that. What the data says: the median 12-month target from 7 analysts implies +16.9% from the last close, and Ticker Nerd's factor model ranks Warrior Met Coal, Inc. 86 out of 100 as at 8 Oct 2026. Analyst targets are third-party estimates and frequently wrong; none of this is personal advice.

What is the HCC stock forecast for 2030?

No analyst covering Warrior Met Coal, Inc. publishes a 2030 price target — Wall Street targets run 12 to 18 months out. Sites quoting a 2030 price for HCC are extrapolating price history, which says nothing about the business. The furthest attributed numbers are the current analyst targets: $98 to $125 over the next 12 months.

How has HCC stock performed over the past year?

Warrior Met Coal, Inc. returned +38.9% over the 12 months to 8 Oct 2026, with dividends reinvested. Past performance does not indicate future returns.

What does Warrior Met Coal, Inc. do?

Warrior Met Coal, Inc. is a U.S.-based metallurgical coal producer focused on the extraction and export of hard coking coal used in steelmaking.

What is the latest news on HCC?

The most recent item we track (Seeking Alpha, 27 Sept 2026): "Warrior Met Coal: A Volume Story Still Priced Like A Coal Price Bet". Warrior Met Coal is increasingly driving earnings growth through volume and cost reductions rather than coking coal price leverage. The Blue Creek Mine's early ramp added a second product line, helping Q2 sales reach a record 3.7 million short tons and lowering unit costs to $92.53 per ton, which compresses forward multiples and offers greater visibility than price-driven peers.

Company

About Warrior Met Coal, Inc.

Warrior Met Coal, Inc. is a U.S.-based metallurgical coal producer focused on the extraction and export of hard coking coal used in steelmaking. The company operates underground mining complexes in Alabama and supplies steel manufacturers in Europe, South America, and Asia. Its core business centers on producing non-thermal steelmaking coal, a specialized input for blast furnace steel production, while also generating additional revenue from the sale of natural gas recovered as a byproduct of mining operations. Warrior Met Coal’s current portfolio is concentrated on mining, processing, and selling premium metallurgical coal, making it an important supplier within the global steel value chain. Headquartered in Brookwood, Alabama, the company serves industrial customers that rely on consistent, high-quality coal feedstock for metal production.

CEO Mr. Walter J. Scheller III · 1,485 employees · United States · https://warriormetcoal.com