
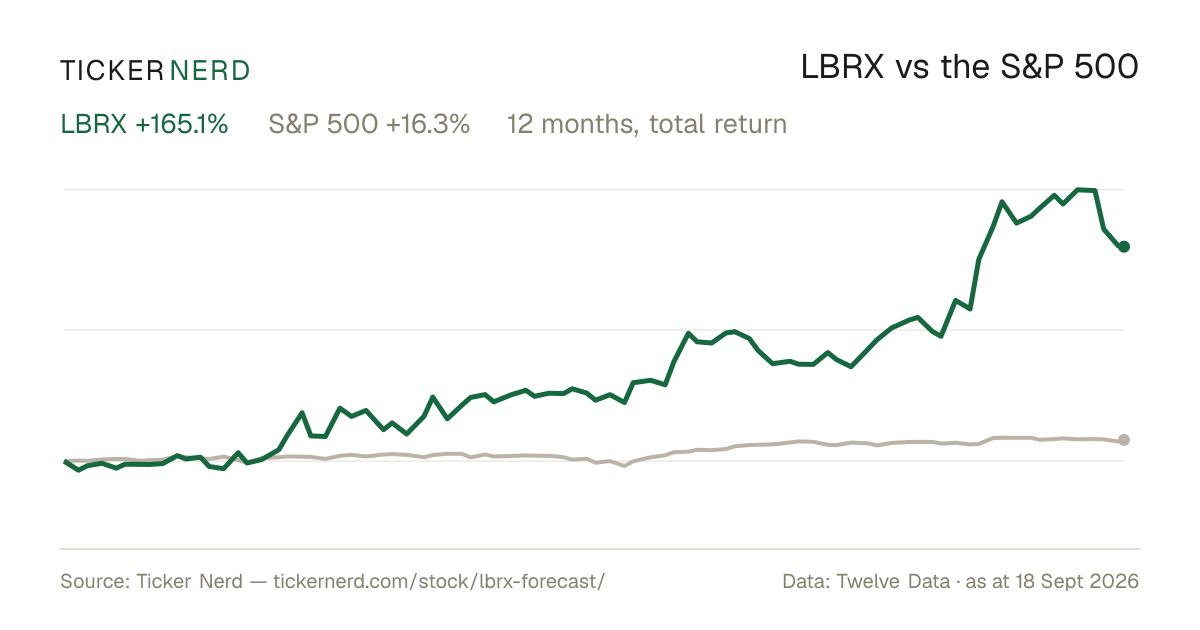
LB Pharmaceuticals: One Methyl Group, Two Enantiomers, And A Bullish $5 Billion Opportunity
Seeking Alpha · 18 Sept 2026positive
Seeking Alpha assigns LB Pharmaceuticals a buy rating with a base-case valuation of $85 per share and potential upside to $150 if Phase 3 trials and clinical differentiation succeed. The article highlights LB-102's N-methyl modification, which enables brain receptor occupancy at lower doses than amisulpride, though the clinical benefit of the R-enantiomer's 5-HT7 activity remains unproven.
Why it matters — LBRX watchers would care because the piece outlines LB-102's differentiation potential and its Phase 3 and clinical-outcome milestones as key factors in the drug's valuation.