MCSMCSCommunication Services · Entertainment

MCS Stock Forecast: Marcus Corp. Price Predictions for 2026-2027

Last close, 14 Oct 2026
$28
+0.04% on the day

The 5 Wall Street analysts covering Marcus Corp. hold a median 12-month price target of $33 — +16.5% from the last close. Ticker Nerd's systematic factor model, run across ~4,600 US stocks, ranks it 98 of 100 as at 14 Oct 2026 — among the strongest tenth. Here, the model and the Street point the same way.

Market cap
$873.2M
Ticker Nerd rank
98 / 100
Median analyst target
$33
Analysts covering
5
Revenue$231.7M+12.5% y/y
Operating income$27.2M
Net income$15.8M
Free cash flow$44.0M
Quarterly, 8 quarters to 30 June 2026 · latest quarter's figure shown
Total return, dividends reinvested
1W
+6.2%
1M
+2.5%
YTD
+84.9%
1Y
+110.6%
From 52W high
−8.7%
From 52W low
+120.8%
$13
$31
52-week range, adjusted closes · the dot is the last close
Ticker Nerd rank

MCS stock analysis: one number for the whole business

Consensus tells you what everyone already believes. The model scores Marcus Corp. on its factor families — the same systematic rank behind the Ticker Nerd portfolio.

Where the model ranks itAs at 14 Oct 2026
98 / 100

Percentile across ~4,600 US stocks on Ticker Nerd’s systematic factor model. Higher is better. How the model is built and tested

Issuance
97
Momentum
94
Revisions
90
Accruals
79
Quality
77
Value
68
Volatility
58
Size
45
Growth
43

Issuance (97): The share count has been shrinking and the company is not leaning on new borrowing.

Growth (43): Sales and profits are flat, shrinking, or growing more slowly than they were.

Built and run by Aslam Ghouse, an ex-Goldman Sachs quant trader with fourteen years in markets.

Wall Street

MCS stock forecast 2026-2027: analyst price targets & predictions

The bullish and bearish analyst opinions on MCS, reported as data — targets and ratings, the market's view beside the model's.

Share price and the analyst range, 12 monthsAdjusted close, US dollars
$10$15$20$25$30$35Jan 26Apr 26Jul 26Oct 26MCSHigh $34Median $33Low $29

Price targets and ratings are third-party analyst estimates, reported here as data. They are not Ticker Nerd forecasts, and they are frequently wrong.

Data provided by Twelve Data

What Wall Street says5 analysts
4 Buy1 Hold0 Sell
Low $29Median $33High $34

The green dot is the last close — the median target sits +16.5% from it.

Recent analyst actionsNewest first

Of the 20 most recent actions, 4 moved their price target up and 0 moved it down.

DateFirmActionRatingTarget
31 July 2026B. Riley SecuritiesDowngradeNeutral$27 → $29
31 July 2026BenchmarkMaintainsBuy$22 → $33
31 July 2026WedbushMaintainsOutperform$23 → $34
11 June 2026B. Riley SecuritiesMaintainsBuy$25 → $27
11 June 2026B. Riley SecuritiesMaintainsBuy—
4 May 2026Barrington ResearchMaintainsOutperform—
30 Apr 2026WedbushMaintainsOutperform—
2 Mar 2026Barrington ResearchMaintainsOutperform—
26 Jan 2026Barrington ResearchMaintainsOutperform—
12 Dec 2025Barrington ResearchMaintainsOutperform—
3 Nov 2025Barrington ResearchMaintainsOutperform—
31 Oct 2025Barrington ResearchMaintainsOutperform—
6 Oct 2025BenchmarkMaintainsBuy—
23 Sept 2025Barrington ResearchMaintainsOutperform—
4 Aug 2025Barrington ResearchReiteratesOutperform—
18 July 2025WedbushInitiatesOutperform—
23 May 2025Barrington ResearchMaintainsOutperform—
6 May 2025Barrington ResearchMaintainsOutperform—
15 Apr 2025Barrington ResearchMaintainsOutperform—
11 Apr 2025BenchmarkReiteratesBuy—

Price targets and ratings are third-party analyst estimates, reported here as data. They are not Ticker Nerd forecasts, and they are frequently wrong.

Market Radar

This page is one stock. Monday covers all of them.

Computed off the Friday close and sent before the US open.

Market Radar reports the week’s largest rank changes across roughly 4,600 US stocks, the factor behind each one, and where the market went. MCS appears on the weeks it earns a place.

Free, every Monday. Unsubscribe any time.

Performance

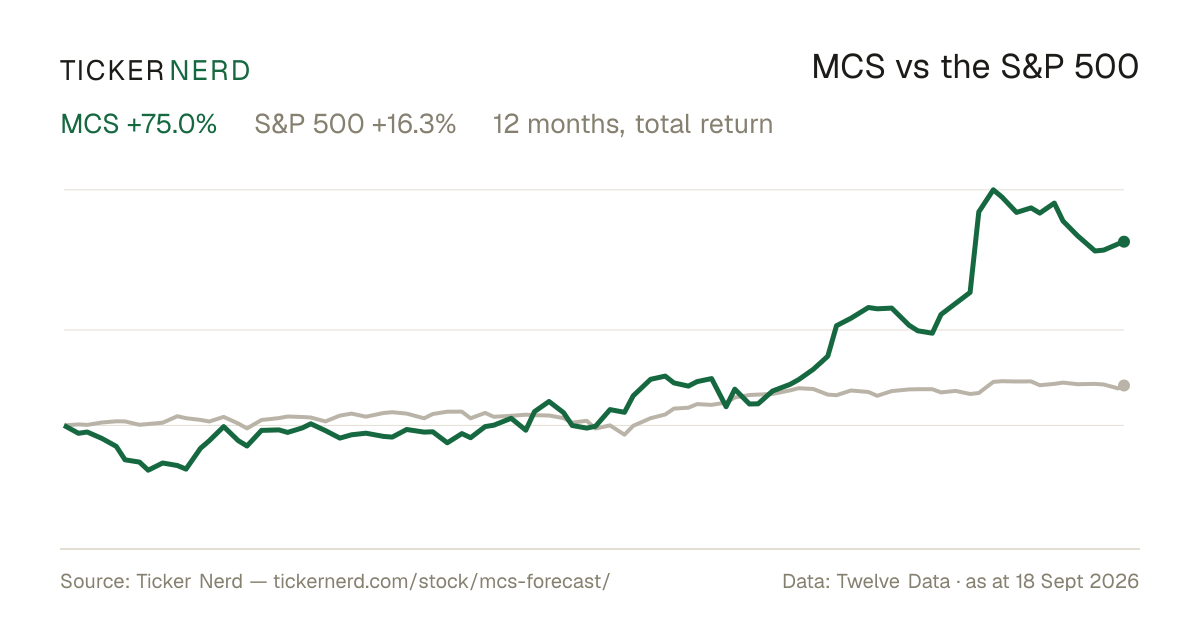
MCS vs the S&P 500

Both lines are total return — dividends reinvested — so the comparison is honest on both sides.

Over the twelve months to 14 Oct 2026, Marcus Corp. returned +110.6% against +17.5% for the S&P 500, dividends included.

MCS vs S&P 500, last 12 monthsTotal return, rebased to 100
100150200Jan 26Apr 26Jul 26Oct 26MCSS&P 500

Download this chart as an image — free to reuse; link this page as the source.

Data provided by Twelve Data

Estimates

MCS analyst estimate revisions

Not the forecast itself — the direction analysts are revising it. Revision direction is one of the model's factor families.

Which way the estimates are movingNext fiscal year
EPS revision, 90 days
+158.8%
Analysts raising
3
Analysts cutting
0
Fundamentals

Marcus Corp. (MCS) financial data

A margin means little on its own. Each bar marks where the figure sits across the whole US universe we score.

Valuation
Trailing P/E
38.3×

Cheaper than 20% of US stocks

Price / sales
1.2×

Cheaper than 65% of US stocks

Price / book
1.9×

Cheaper than 45% of US stocks

EV / EBITDA
10.7×

Cheaper than 35% of US stocks

Growth & margins
Revenue growth (YoY)
12.8%

Higher than 58% of US stocks

Earnings growth (YoY)
116.4%

Higher than 85% of US stocks

Gross margin
41.2%

Higher than 51% of US stocks

Operating margin
12.1%

Higher than 68% of US stocks

Net margin
3.0%

Higher than 55% of US stocks

Returns & dividend
Return on equity
5.0%

Higher than 54% of US stocks

Return on assets
2.3%

Higher than 60% of US stocks

Dividend yield
1.3%

Higher than 73% of US dividend payers

Bars mark the percentile across the ~4,600 US stocks Ticker Nerd covers, among those reporting the figure.

Key statistics

Marcus Corp. (MCS) statistics: revenue, profit & scale

The headline figures, each with its date. Every row carries its own link — cite it straight from here.

  • Marcus Corp. has a market value of $873.2M and an enterprise value of $1.1B.

  • Revenue in the twelve months to 30 June 2026: $789.8M. The latest quarter grew 12.8% year on year.

  • Net income over the same four quarters: $22.7M, a 2.9% net margin.

  • Diluted earnings per share, trailing twelve months: $0.71.

  • Free cash flow in the twelve months to 30 June 2026: $66.7M, after $59.9M of capital spending.

  • Marcus Corp. spent $9.6M on dividends in the twelve months to 30 June 2026.

  • Shares outstanding: 30.8M.

  • Trailing P/E: 38.3×; forward P/E: 33.7× — the forward figure prices analyst consensus estimates, not reported earnings.

  • Forward dividend yield: 1.27%, paying out 43% of earnings.

  • Marcus Corp. employs 2,349 people — $336K of revenue per employee.

Statement figures: company filings via Twelve Data, four quarters to 30 June 2026 · market figures as at 15 Oct 2026

Data provided by Twelve Data

Peers

MCS vs competitors

The nearest names by industry and size, scored by the same model — like for like.

Its peer group, ranked by the same modelEntertainment
CompanyMarket capTKN rank
MCSMarcus Corp.$873.2M
98
ANGXAngel Studios, Inc.$659.4M
25
RSVRReservoir Media, Inc.$634.9M
38
AMCXAMC Global Media, Inc.$466.6M
88
STRZStarz Entertainment Corp.$427.6M
4
AMCAMC Entertainment Holdings, Inc.$2.6B
55
IMAXIMAX Corp.$2.8B
91

Look up any of the roughly 4,600 stocks we score.

The rank is the raw material. Whether the rules would actually own Marcus Corp. — and when they’d sell — is the membership. See the Ticker Nerd 20 →

News

Latest MCS news & analysis

The Marcus Corporation: Still Worth The Ticket

Seeking Alpha · 6 Oct 2026positive

Seeking Alpha reiterated a Buy rating on Marcus Corporation and raised its price target to the low-to-mid $30s, citing double-digit upside. The company's theatre business outperformed the domestic box office with revenue up 14.4% and adjusted EBITDA margin at 18.7% LTM, while its Hotels & Resorts segment posted 9.6% revenue growth and a 13.9% RevPAR increase.

Why it matters — The report highlights strong performance across both of Marcus's segments, suggesting the company is outpacing industry benchmarks in its theatre and hotel operations.

4 Leisure Stocks Offering Growth Amid Industry Pressures

Zacks Investment Research · 29 Sept 2026positive

Zacks Investment Research highlighted Marcus among four leisure stocks (alongside Life Time Group, Marriott Vacations, and AMC) that are finding growth amid industry pressures. The report cites demand, pricing, premium offerings, and efficiency as key drivers of their growth.

Why it matters — MCS watchers would care because the report identifies Marcus as one of a select group of leisure companies managing to grow despite broader industry headwinds, signaling resilience in its business model.

Marcus Theatres Appoints Shannah Miller Senior Vice President of Marketing and Sales

Business Wire · 28 Sept 2026neutral

Marcus Theatres, a division of Marcus Corporation, announced the appointment of Shannah Miller as senior vice president of marketing and sales, effective October 19. Miller brings more than 20 years of experience in entertainment and content distribution, with expertise in marketing strategy, audience development, partnerships, and revenue growth.

Why it matters — MCS watchers would care because this reflects a change in the leadership of its theatre division's marketing and sales function, which could influence how the company approaches audience development and revenue.

AMC vs. MCS: Which Theater Stock Is the Better Buy Today?

Zacks Investment Research · 18 Sept 2026positive

A Zacks Investment Research article compares Marcus Corp. with AMC Entertainment, presenting Marcus as having the advantage, citing theater outperformance, hotel diversification, and low leverage as supporting stronger near-term momentum.

Why it matters — For MCS watchers, the piece highlights favorable factors such as theater performance, hotel diversification, and low leverage that are positioned to support the company's momentum.

Marcus Stock Surges 75% YTD: Should Investors Ride the Rally?

Zacks Investment Research · 9 Sept 2026positive

Marcus Corp. (MCS) stock has surged 75% year-to-date, supported by record summer theater results, stronger hotel demand, and rising cash flow. The company's valuation remains below the industry average.

Why it matters — The report highlights improving operational fundamentals across MCS's theater and hotel segments, along with below-industry valuation, which could be of interest to investors tracking the company's momentum.

FAQ

Frequently asked questions about MCS stock

What is the MCS stock price forecast for 2026-2027?

The 5 Wall Street analysts covering Marcus Corp. have a median 12-month price target of $33, with estimates ranging from $29 to $34. These are third-party analyst estimates, not Ticker Nerd forecasts, and they are frequently wrong.

Is MCS stock a buy right now?

Of the 5 analysts covering Marcus Corp., 4 rate it a Buy, 1 a Hold and 0 a Sell. Ticker Nerd's systematic factor model ranks Marcus Corp. 98 out of 100 across roughly 4,600 US stocks as at 14 Oct 2026. None of this is personal advice — it does not consider your circumstances.

How does Ticker Nerd's model rank MCS?

As at 14 Oct 2026, Marcus Corp. ranks 98 out of 100 on Ticker Nerd's systematic factor model — a percentile across roughly 4,600 US stocks, built from its factor families. Its strongest factor family is Issuance (97 of 100).

Will MCS stock go up?

No one can know that. What the data says: the median 12-month target from 5 analysts implies +16.5% from the last close, and Ticker Nerd's factor model ranks Marcus Corp. 98 out of 100 as at 14 Oct 2026. Analyst targets are third-party estimates and frequently wrong; none of this is personal advice.

What is the MCS stock forecast for 2030?

No analyst covering Marcus Corp. publishes a 2030 price target — Wall Street targets run 12 to 18 months out. Sites quoting a 2030 price for MCS are extrapolating price history, which says nothing about the business. The furthest attributed numbers are the current analyst targets: $29 to $34 over the next 12 months.

How has MCS stock performed over the past year?

Marcus Corp. returned +110.6% over the 12 months to 14 Oct 2026, with dividends reinvested. Past performance does not indicate future returns.

What does Marcus Corp. do?

The Marcus Corporation is an American entertainment and hospitality company headquartered in Milwaukee, Wisconsin. It operates through two main business segments: Marcus Theatres and Marcus Hotels & Resorts.

What is the latest news on MCS?

The most recent item we track (Seeking Alpha, 6 Oct 2026): "The Marcus Corporation: Still Worth The Ticket". Seeking Alpha reiterated a Buy rating on Marcus Corporation and raised its price target to the low-to-mid $30s, citing double-digit upside. The company's theatre business outperformed the domestic box office with revenue up 14.4% and adjusted EBITDA margin at 18.7% LTM, while its Hotels & Resorts segment posted 9.6% revenue growth and a 13.9% RevPAR increase.

Company

About Marcus Corp.

The Marcus Corporation is an American entertainment and hospitality company headquartered in Milwaukee, Wisconsin. It operates through two main business segments: Marcus Theatres and Marcus Hotels & Resorts. Theatres includes multiscreen movie theatres, family entertainment centers, and branded cinema concepts such as Marcus Theatres, Movie Tavern by Marcus, and BistroPlex. The hospitality segment owns, operates, and manages full-service hotels and resorts, along with related property services. The Marcus Corporation also provides hospitality management functions such as housekeeping, maintenance, and check-in services, supporting vacation ownership and condominium hotel operations. With a portfolio that spans leisure, lodging, and real estate, The Marcus Corporation plays a notable role in regional entertainment and hotel markets across the United States.

CEO Mr. Gregory S. Marcus J.D. · 2,349 employees · United States · https://www.marcuscorp.com