Marsh & McLennan: Challenging Operating Environment Likely To Persist Ahead
Seeking Alpha · 16 Oct 2026negative
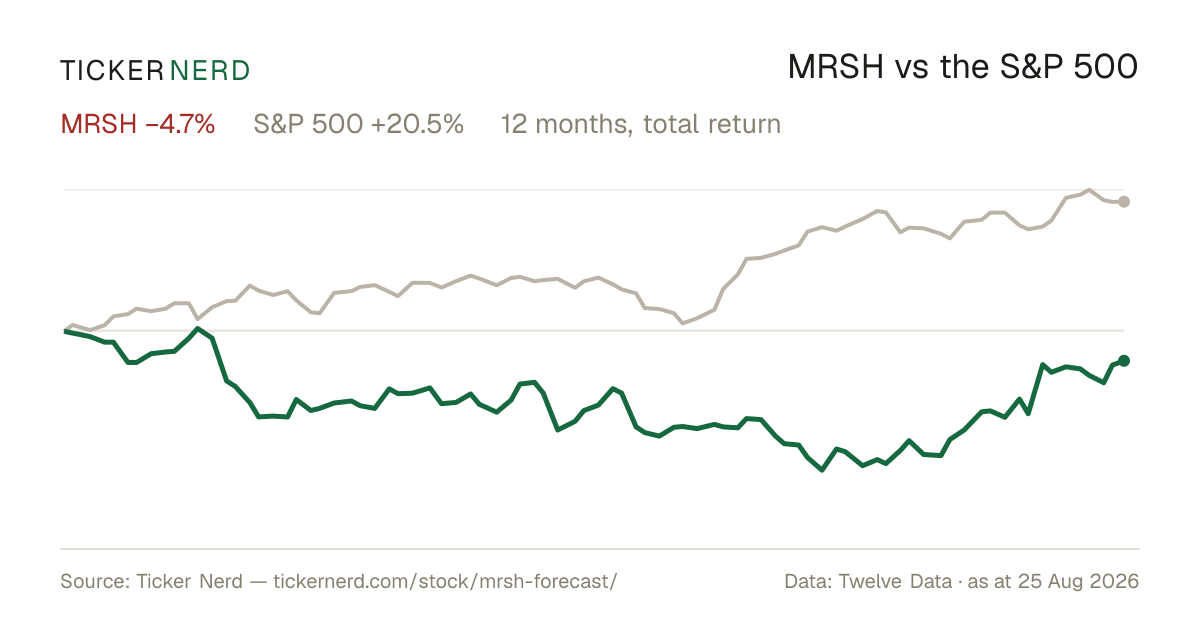
Marsh & McLennan beat Q3 2026 revenue and EPS estimates, but growth slowed amid P&C pricing headwinds and reinsurance weakness. The article notes ongoing margin pressure from inflation and wages, alongside a higher cost-cutting target of $600 million by 2028, and a downgrade to Hold.
Why it matters — MRSH watchers may want to track whether cost reductions can offset continued operating-margin pressure and cyclical weakness.