
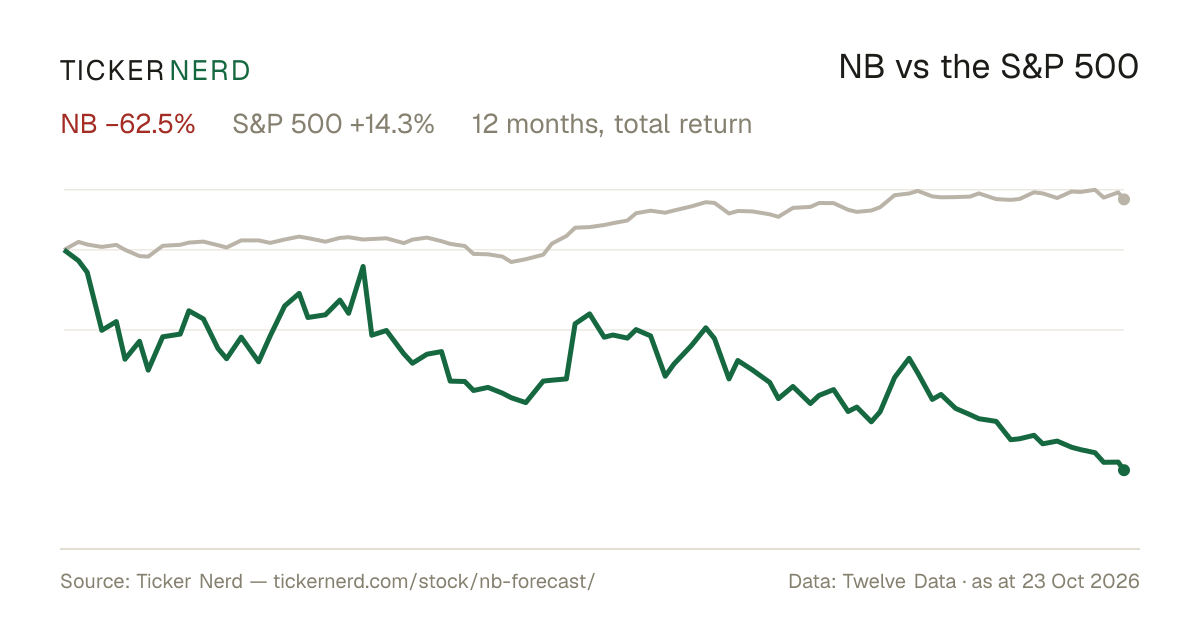
NioCorp: The Bear Case Is Real, But At $3 I'm Still Buying
Seeking Alpha · 24 Oct 2026negative
The Seeking Alpha article weighs four bearish arguments about NioCorp, noting its roughly $405 million in cash against a market valuation of about $444 million. It says rising capital needs are a priced risk, while concerns around scandium, dilution and EXIM partly hold; scandium accounts for 38% of study revenue, lacks a binding buyer, and the cited Chinese price is a quarter of the study price.
Why it matters — The article highlights uncertainty around scandium pricing and buyers, alongside capital, dilution and EXIM risks, for investors following NB.