POSTPOSTConsumer Defensive · Packaged Foods

POST Stock Forecast: Post Holdings, Inc. Price Predictions for 2026-2027

Last close, 2 Oct 2026
$73
−0.37% on the day

The 7 Wall Street analysts covering Post Holdings, Inc. hold a median 12-month price target of $102 — +40.6% from the last close. Ticker Nerd's systematic factor model, run across ~4,600 US stocks, ranks it 58 of 100 as at 1 Oct 2026 — in the upper half.

Market cap
$3.3B
Ticker Nerd rank
58 / 100
Median analyst target
$102
Analysts covering
7
Revenue$1.9B−1.8% y/y
Operating income$189.3M
Net income$63.6M
Free cash flow$131.2M
Quarterly, 8 quarters to 30 June 2026 · latest quarter's figure shown
Total return, dividends reinvested
1W
−0.8%
1M
−13.9%
YTD
−26.7%
1Y
−32.1%
From 52W high
−36.7%
From 52W low
0.0%
$73
$115
52-week range, adjusted closes · the dot is the last close
Ticker Nerd rank

POST stock analysis: one number for the whole business

Consensus tells you what everyone already believes. The model scores Post Holdings, Inc. on its factor families — the same systematic rank behind the Ticker Nerd portfolio.

Where the model ranks itAs at 1 Oct 2026
58 / 100

Percentile across ~4,600 US stocks on Ticker Nerd’s systematic factor model. Higher is better. How the model is built and tested

Value
91
Volatility
87
Issuance
73
Accruals
69
Quality
65
Revisions
44
Growth
44
Size
28
Momentum
16

Value (91): The shares cost little relative to the profits and assets behind them — which can mean the market is too gloomy, or that the business really is in trouble.

Momentum (16): The shares have been drifting down relative to others.

Built and run by Aslam Ghouse, an ex-Goldman Sachs quant trader with fourteen years in markets.

Wall Street

POST stock forecast 2026-2027: analyst price targets & predictions

The bullish and bearish analyst opinions on POST, reported as data — targets and ratings, the market's view beside the model's.

Share price and the analyst range, 12 monthsAdjusted close, US dollars
$70$80$90$100$110$120$130Jan 26Apr 26Jul 26Oct 26POSTHigh $125Median $102Low $86

Price targets and ratings are third-party analyst estimates, reported here as data. They are not Ticker Nerd forecasts, and they are frequently wrong.

Data provided by Twelve Data

What Wall Street says7 analysts
5 Buy2 Hold0 Sell
Low $86Median $102High $125

The green dot is the last close — the median target sits +40.6% from it.

Recent analyst actionsNewest first

Of the 20 most recent actions, 0 moved their price target up and 8 moved it down.

DateFirmActionRatingTarget
11 Aug 2026BarclaysMaintainsOverweight$106 → $95
10 Aug 2026Evercore ISI GroupMaintainsOutperform$128 → $121
10 Aug 2026JP MorganMaintainsOverweight$116 → $99
10 Aug 2026Wells FargoMaintainsEqual-Weight$98 → $86
23 July 2026Evercore ISI GroupMaintainsOutperform—
23 July 2026Evercore ISI GroupMaintainsOutperform$131 → $128
21 July 2026BarclaysMaintainsOverweight$119 → $106
21 July 2026BarclaysMaintainsOverweight—
20 July 2026JP MorganMaintainsOverweight$119 → $116
20 July 2026JP MorganMaintainsOverweight—
8 July 2026Wells FargoMaintainsEqual-Weight$110 → $98
8 July 2026Wells FargoMaintainsEqual-Weight—
20 Apr 2026JP MorganMaintainsOverweight—
14 Apr 2026BarclaysMaintainsOverweight—
14 Apr 2026BTIGInitiatesNeutral—
8 Apr 2026Wells FargoMaintainsEqual-Weight—
9 Feb 2026Wells FargoMaintainsEqual-Weight—
1 Dec 2025MizuhoMaintainsOutperform—
25 Nov 2025BarclaysMaintainsOverweight—
24 Nov 2025Evercore ISI GroupMaintainsOutperform—

Price targets and ratings are third-party analyst estimates, reported here as data. They are not Ticker Nerd forecasts, and they are frequently wrong.

Market Radar

This page is one stock. Monday covers all of them.

Computed off the Friday close and sent before the US open.

Market Radar reports the week’s largest rank changes across roughly 4,600 US stocks, the factor behind each one, and where the market went. POST appears on the weeks it earns a place.

Free, every Monday. Unsubscribe any time.

Performance

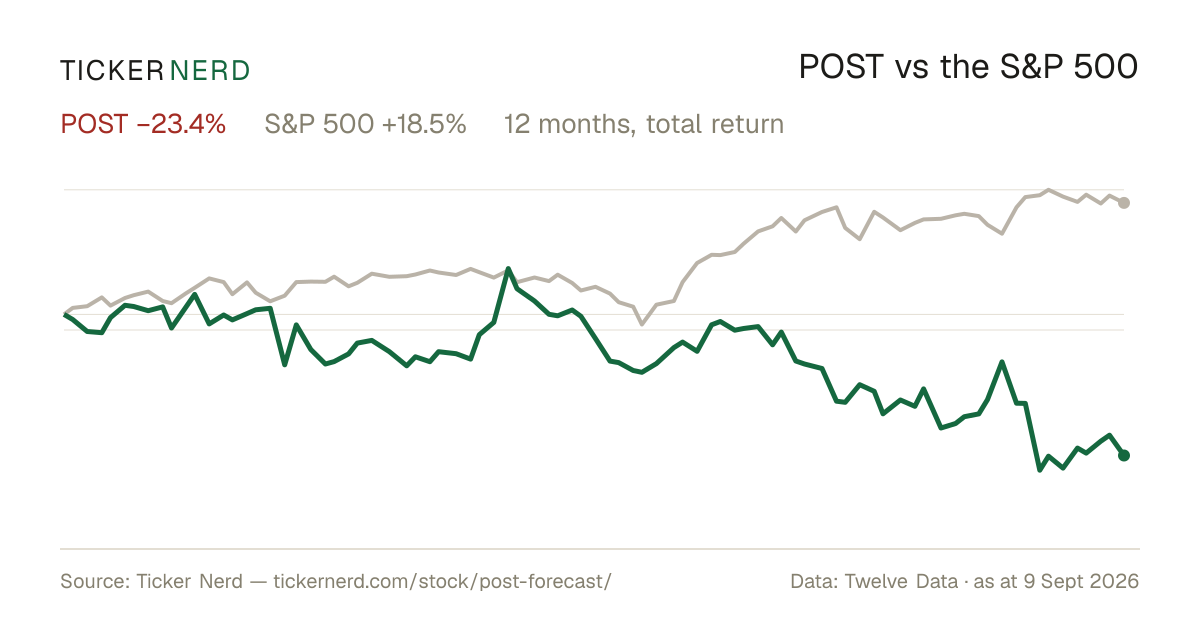
POST vs the S&P 500

Both lines are total return — dividends reinvested — so the comparison is honest on both sides.

Over the twelve months to 2 Oct 2026, Post Holdings, Inc. returned −32.1% against +15.4% for the S&P 500, dividends included.

POST vs S&P 500, last 12 monthsTotal return, rebased to 100
60708090100110120Jan 26Apr 26Jul 26Oct 26POSTS&P 500

Download this chart as an image — free to reuse; link this page as the source.

Data provided by Twelve Data

Estimates

POST analyst estimate revisions

Not the forecast itself — the direction analysts are revising it. Revision direction is one of the model's factor families.

Which way the estimates are movingNext fiscal year
EPS revision, 90 days
−0.8%
Analysts raising
3
Analysts cutting
4
Fundamentals

Post Holdings, Inc. (POST) financial data

A margin means little on its own. Each bar marks where the figure sits across the whole US universe we score.

Valuation
Trailing P/E
13.2×

Cheaper than 49% of US stocks

Price / sales
0.4×

Cheaper than 85% of US stocks

Price / book
1.0×

Cheaper than 70% of US stocks

EV / EBITDA
7.3×

Cheaper than 47% of US stocks

Growth & margins
Revenue growth (YoY)
−1.8%

Higher than 24% of US stocks

Earnings growth (YoY)
−41.7%

Higher than 12% of US stocks

Gross margin
29.1%

Higher than 33% of US stocks

Operating margin
10.3%

Higher than 64% of US stocks

Net margin
3.5%

Higher than 56% of US stocks

Returns & dividend
Return on equity
8.3%

Higher than 59% of US stocks

Return on assets
4.2%

Higher than 72% of US stocks

Dividend yield
—

Bars mark the percentile across the ~4,600 US stocks Ticker Nerd covers, among those reporting the figure.

Key statistics

Post Holdings, Inc. (POST) statistics: revenue, profit & scale

The headline figures, each with its date. Every row carries its own link — cite it straight from here.

  • Post Holdings, Inc. has a market value of $3.3B and an enterprise value of $10.6B.

  • Revenue in the twelve months to 30 June 2026: $8.4B. The latest quarter shrank 1.8% year on year.

  • Net income over the same four quarters: $293.7M, a 3.5% net margin.

  • Diluted earnings per share, trailing twelve months: $5.44.

  • Free cash flow in the twelve months to 30 June 2026: $553.1M.

  • Post Holdings, Inc. spent $1.2B on share buybacks in the twelve months to 30 June 2026.

  • Shares outstanding: 44.6M.

  • Trailing P/E: 13.2×; forward P/E: 10.1× — the forward figure prices analyst consensus estimates, not reported earnings.

  • Post Holdings, Inc. employs 13,180 people — $638K of revenue per employee.

Statement figures: company filings via Twelve Data, four quarters to 30 June 2026 · market figures as at 2 Oct 2026

Data provided by Twelve Data

Peers

POST vs competitors

The nearest names by industry and size, scored by the same model — like for like.

Its peer group, ranked by the same modelPackaged Foods
CompanyMarket capTKN rank
POSTPost Holdings, Inc.$3.3B
58
FRPTFreshpet, Inc.$2.8B
63
MZTIThe Marzetti Co.$2.7B
35
CENTACentral Garden & Pet Co.$2.2B
94
UTZUTZ Brands, Inc.$2.0B
54
LWLamb Weston Holdings, Inc.$5.7B
77
CPBThe Campbell's Co.$5.8B
34

Look up any of the roughly 4,600 stocks we score.

The rank is the raw material. Whether the rules would actually own Post Holdings, Inc. — and when they’d sell — is the membership. See the Ticker Nerd 20 →

News

Latest POST news & analysis

Post Holdings: The 2027 Earnings Decline Looks Worse Than It Is

Seeking Alpha · 21 Sept 2026positive

Post Holdings is rated Buy after a 35% share decline, with shares trading at roughly 10x earnings and 6.9x forward EBITDA. Management is shifting capital allocation from aggressive buybacks toward debt reduction, and fiscal 2027 is expected to be a reset year, with normalized Foodservice EBITDA and cost savings supporting an EPS rebound in 2028.

Why it matters — A POST watcher would care because the article frames the expected 2027 earnings decline as a temporary reset that could lead to an EPS rebound in 2028, while highlighting a strategic shift from buybacks to debt reduction.

Post Holdings: A Cheap Food Stock The Market Keeps Ignoring

Seeking Alpha · 21 Sept 2026positive

Seeking Alpha maintains a Strong Buy rating on Post Holdings, arguing the stock trades at an unjustified discount despite resilient free cash flow and a diversified portfolio. The company is shifting its capital allocation from aggressive buybacks (17% fiscal YTD) toward debt reduction to improve its fundamentals and credit profile as refinancing risks rise.

Why it matters — POST watchers would care because the article highlights a shift in capital allocation from buybacks to debt reduction aimed at strengthening the company's credit profile as refinancing risks rise.

Can Post Holdings' Foodservice Growth Counter Retail Headwinds?

Zacks Investment Research · 16 Sept 2026positive

Post Holdings reported Foodservice segment strength that lifted its fiscal third-quarter 2026 results. The company anticipates this growth could help offset retail headwinds while it targets stable fiscal 2027 EBITDA.

Why it matters — A Post Holdings watcher would care because the balance between Foodservice momentum and retail pressures is central to the company's near-term earnings outlook and its fiscal 2027 EBITDA target.

Post Holdings' Premium Cereal Gains Share Amid Category Pressure

Zacks Investment Research · 8 Sept 2026neutral

Post Holdings' cereal business continues to face pressure, though its premium brands and assortment changes are helping the company close the gap with the broader category.

Why it matters — POST watchers would care because the company's premium brand strategy is helping mitigate ongoing cereal category headwinds.

Post Holdings Q3 Earnings Beat: Can Foodservice Drive 2027?

Zacks Investment Research · 24 Aug 2026neutral

Post Holdings beat Q3 earnings estimates as its Foodservice segment strengthened. However, fiscal 2027 EBITDA is expected to remain generally flat.

Why it matters — A POST watcher would care because the earnings beat signals near-term strength in Foodservice, while the flat fiscal 2027 EBITDA outlook points to limited growth expectations ahead.

FAQ

Frequently asked questions about POST stock

What is the POST stock price forecast for 2026-2027?

The 7 Wall Street analysts covering Post Holdings, Inc. have a median 12-month price target of $102, with estimates ranging from $86 to $125. These are third-party analyst estimates, not Ticker Nerd forecasts, and they are frequently wrong.

Is POST stock a buy right now?

Of the 7 analysts covering Post Holdings, Inc., 5 rate it a Buy, 2 a Hold and 0 a Sell. Ticker Nerd's systematic factor model ranks Post Holdings, Inc. 58 out of 100 across roughly 4,600 US stocks as at 1 Oct 2026. None of this is personal advice — it does not consider your circumstances.

How does Ticker Nerd's model rank POST?

As at 1 Oct 2026, Post Holdings, Inc. ranks 58 out of 100 on Ticker Nerd's systematic factor model — a percentile across roughly 4,600 US stocks, built from its factor families. Its strongest factor family is Value (91 of 100).

Will POST stock go up?

No one can know that. What the data says: the median 12-month target from 7 analysts implies +40.6% from the last close, and Ticker Nerd's factor model ranks Post Holdings, Inc. 58 out of 100 as at 1 Oct 2026. Analyst targets are third-party estimates and frequently wrong; none of this is personal advice.

What is the POST stock forecast for 2030?

No analyst covering Post Holdings, Inc. publishes a 2030 price target — Wall Street targets run 12 to 18 months out. Sites quoting a 2030 price for POST are extrapolating price history, which says nothing about the business. The furthest attributed numbers are the current analyst targets: $86 to $125 over the next 12 months.

How has POST stock performed over the past year?

Post Holdings, Inc. returned -32.1% over the 12 months to 2 Oct 2026, with dividends reinvested. Past performance does not indicate future returns.

What does Post Holdings, Inc. do?

Post Holdings, Inc. Common Stock represents ownership in Post Holdings, Inc., a consumer packaged goods holding company based in St.

What is the latest news on POST?

The most recent item we track (Seeking Alpha, 21 Sept 2026): "Post Holdings: The 2027 Earnings Decline Looks Worse Than It Is". Post Holdings is rated Buy after a 35% share decline, with shares trading at roughly 10x earnings and 6.9x forward EBITDA. Management is shifting capital allocation from aggressive buybacks toward debt reduction, and fiscal 2027 is expected to be a reset year, with normalized Foodservice EBITDA and cost savings supporting an EPS rebound in 2028.

Company

About Post Holdings, Inc.

Post Holdings, Inc. Common Stock represents ownership in Post Holdings, Inc., a consumer packaged goods holding company based in St. Louis, Missouri. Post Holdings focuses on branded food and beverage products sold through grocery, club, drug, mass merchandise, foodservice, and e-commerce channels. Its current business is organized across four segments: Post Consumer Brands, Weetabix, Foodservice, and Refrigerated Retail. The company’s portfolio includes ready-to-eat cereals, granola, pet food, nut butters, egg products, potato products, cheese, sausage, and other refrigerated and shelf-stable foods. Post Holdings serves household and commercial customers in the United States and internationally, making it a significant participant in the packaged foods market and a diversified supplier across everyday food categories.

CEO Mr. Mike McCoy · 13,180 employees · United States · https://www.postholdings.com