
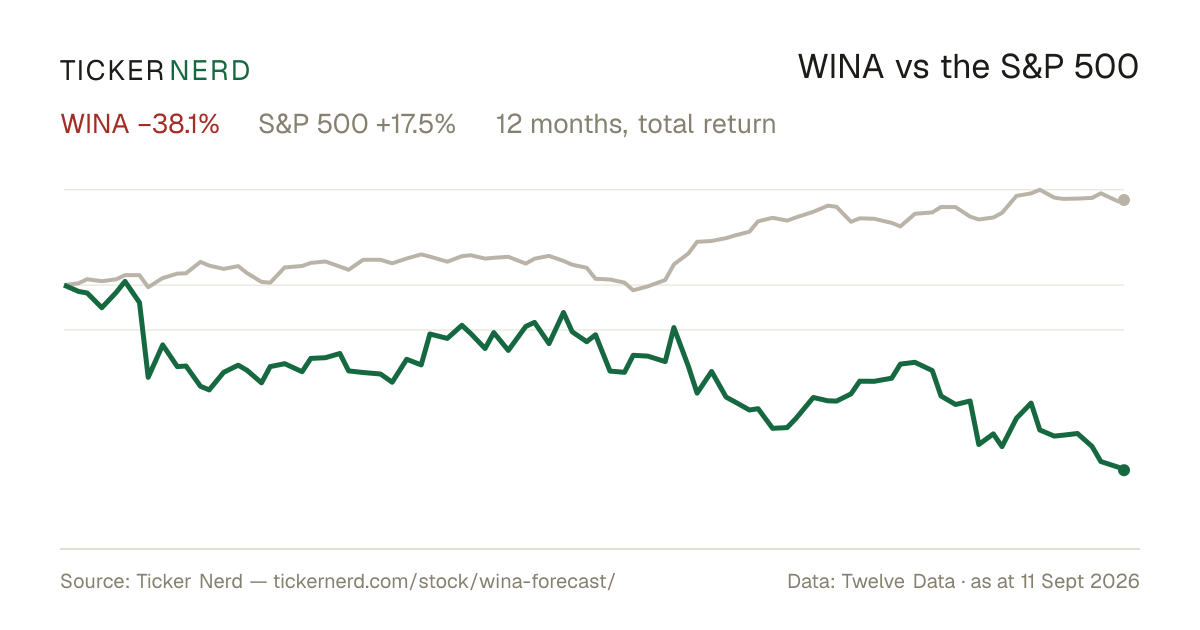
Winmark Is Still Trading At A Premium After Its Plunge
Seeking Alpha · 2 Oct 2026negative
Winmark Corporation remains rated a soft 'Sell' due to persistent overvaluation despite a 22.5% share price decline since May. Revenue and franchise location counts rose, but first-half 2026 profits and cash flows fell year-over-year, and voluntary SG&A investments pressured near-term margins despite mixed operating cash flow and EBITDA trends.
Why it matters — WINA watchers would care because the analysis indicates the stock still trades at a premium while recent profitability and cash flow metrics have weakened, suggesting potential downside risk from the current valuation.