
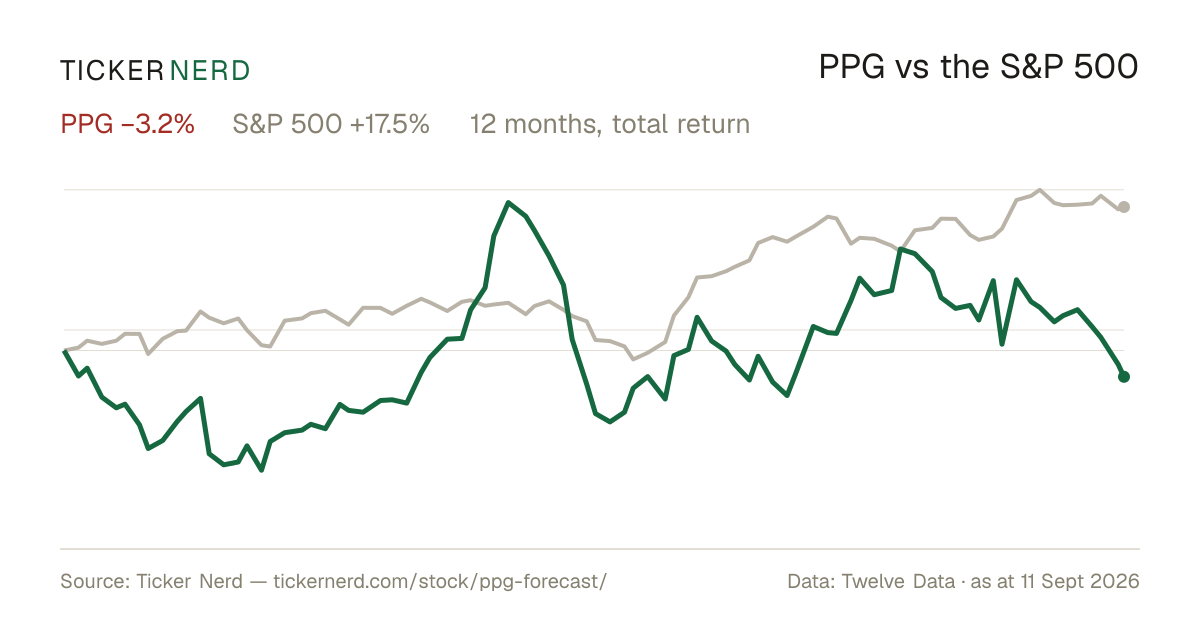
PPG Industries: Prefer To Wait For A Cleaner Picture
Seeking Alpha · 30 Sept 2026neutral
PPG Industries was rated Hold after underperforming the market and facing margin pressures, especially in its high-margin Automotive Refinish segment. Q2 revenue grew 7% to approximately $4.5B with 4% organic growth, but EPS was flat as weakness in Automotive Refinish offset gains elsewhere.
Why it matters — A PPG watcher would care because the company's high-margin Automotive Refinish segment is pressuring profitability and share performance, even as overall revenue grows and valuation appears discounted relative to its five-year average.