
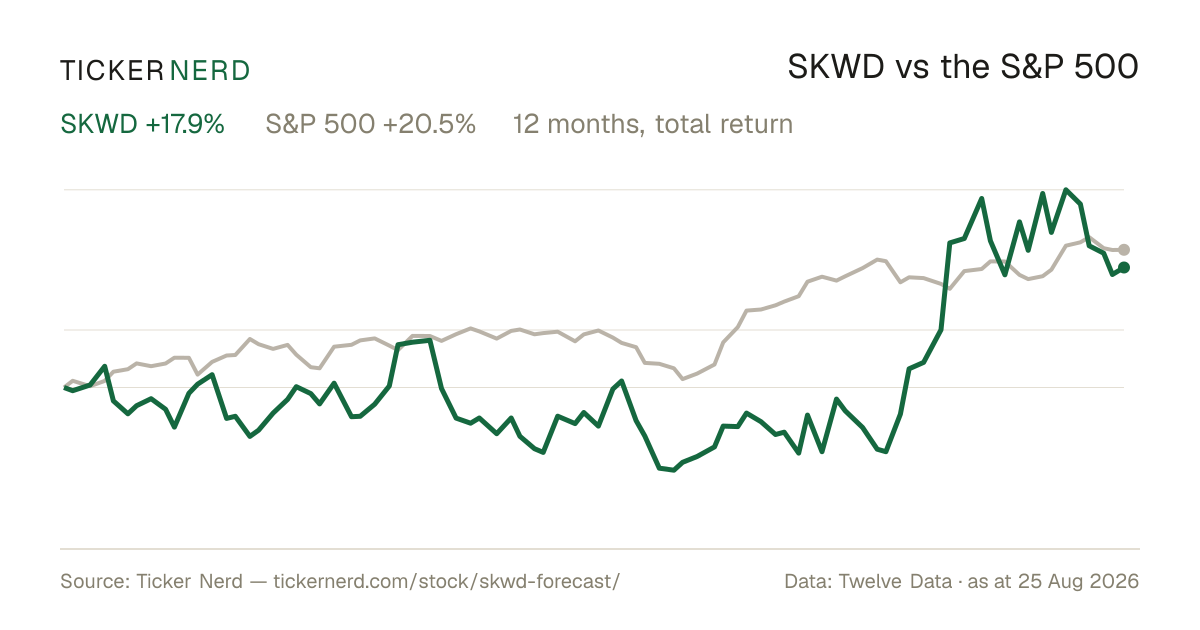
Skyward Specialty Seems Now To Be Fairly Valued
Seeking Alpha · 18 Sept 2026neutral
Skyward Specialty delivered resilient H1 2026 results with strong premium growth and robust underwriting profitability, according to a Seeking Alpha analysis. The Apollo acquisition boosted scale and investment income, though integration challenges persist around Apollo's higher expense ratio, and the company prioritizes balance sheet deleveraging over capital returns while continuing share buybacks with no near-term dividend.
Why it matters — SKWD watchers would care because the analysis highlights the company's strong recent performance and growth via the Apollo acquisition while flagging integration and expense-ratio challenges and a conservative capital-return posture.