
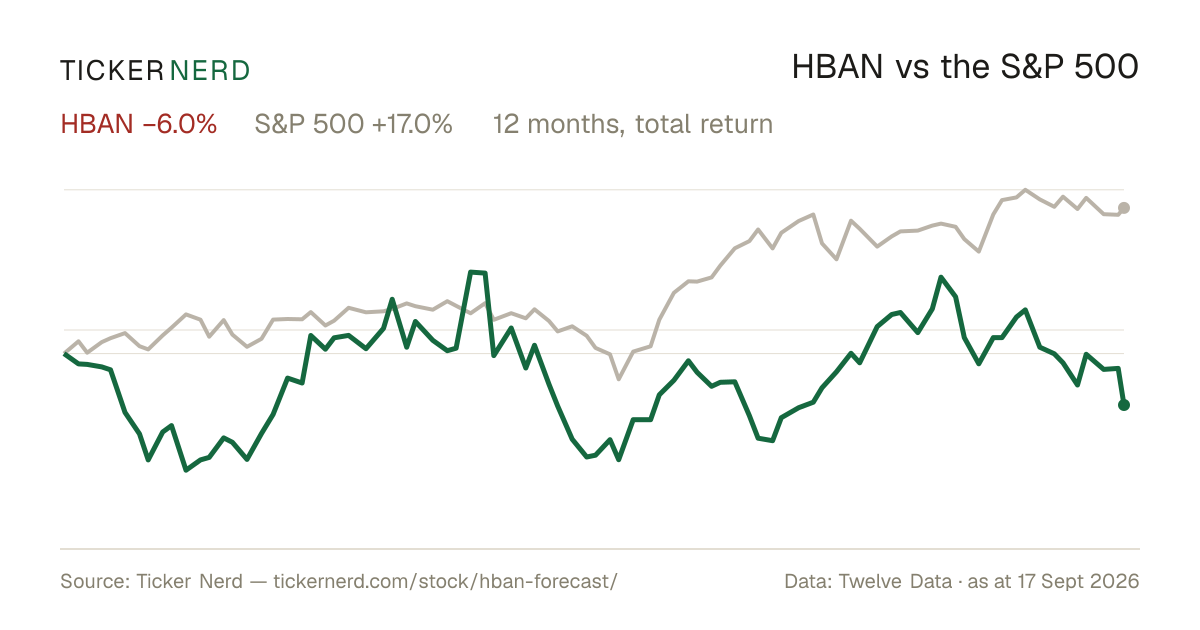
Huntington Bancshares: Interest Rate Pressures Reduce Upside
Seeking Alpha · 1 Oct 2026negative
Huntington Bancshares faces margin and growth headwinds from higher interest rates, prompting it to cut its 2027 earnings outlook and net interest income growth due to rising deposit costs and slower loan growth. The bank maintains a solid strategic footprint after recent M&A-driven expansion, with adequate but not excessive capital and a secure 4.1% dividend, though buybacks could slow if rates rise further.
Why it matters — A HBAN watcher would care because higher interest rates are pressuring the bank's margins, growth, and earnings outlook, potentially slowing buybacks even as the dividend remains protected.