Seeking Alpha · 2 Oct 2026positive
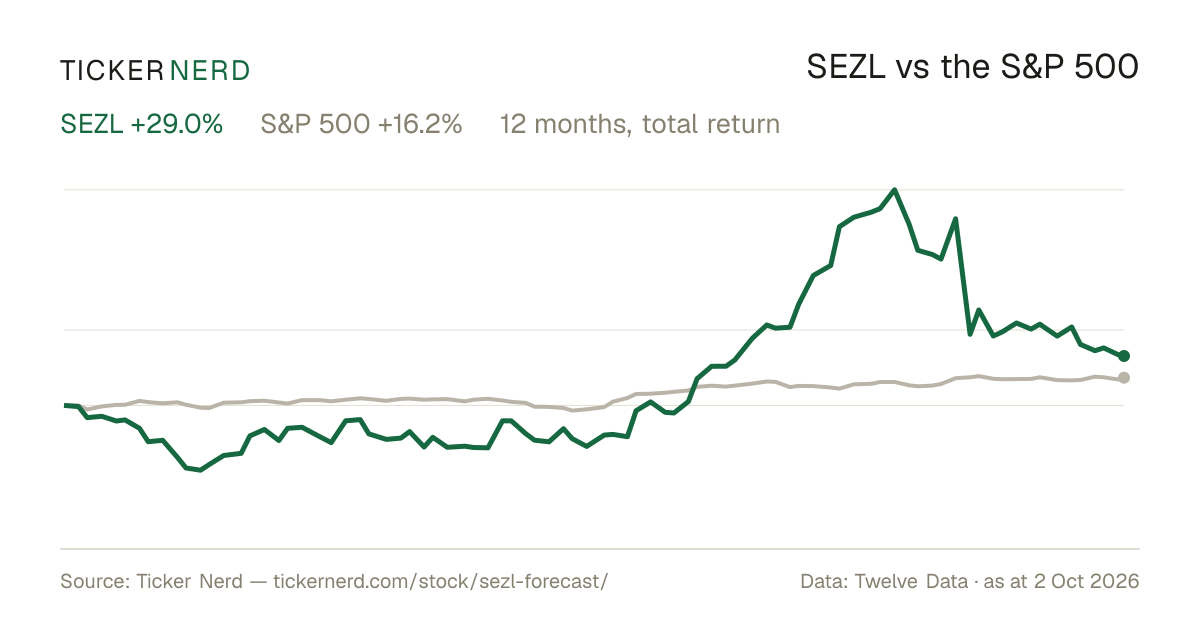
Sezzle is highlighted as an attractive investment after a 45% pullback, with strong multi-year revenue and earnings growth expected. New product launches, Sezzle Send and SezzleCash, are positioned to drive user acquisition, retention, and platform virality, while profitability metrics (ROE 89%, ROIC 64%, ROA 35%) far exceed sector medians.
Why it matters — SEZL watchers would care because the article points to strong financial returns, new growth-driving products, and a potential buying opportunity following a recent stock-price decline.
24/7 Wall Street · 30 Sept 2026negative
The article compares September performance among three buy now, pay later stocks: Affirm, Klarna, and Sezzle. Affirm was the relative winner despite falling 10.5% to $69.61, Klarna declined 12.5% to $12.42, and Sezzle fell 13%.
Why it matters — Sezzle watchers would care because the report shows Sezzle was the weakest performer among the three BNPL stocks in September.
Zacks Investment Research · 30 Sept 2026positive
Sezzle's On-Demand offering is being highlighted for its ability to attract enterprise merchants through competitive buy-now-pay-later pricing, while also creating a pathway toward deeper subscriber engagement for the company.
Why it matters — A SEZL watcher would care because On-Demand's enterprise appeal and subscriber-engagement potential could broaden the company's merchant base and deepen customer relationships.
Zacks Investment Research · 30 Sept 2026positive
Zacks Investment Research highlighted Sezzle Inc. (SEZL) as a strong growth stock, noting that the Zacks Style Scores—a feature of its premium research service—can help investors identify strong stocks across value, growth, and momentum categories.
Why it matters — SEZL watchers would care because the piece signals that the company is being recognized as a strong growth stock by Zacks' research tools.
Seeking Alpha · 30 Sept 2026positive
A Seeking Alpha article argues Sezzle's recent sell-off presents an opportunity, citing strong growth with subscribers up 76.4%, transactions up 32%, and quarterly GMV up 38% year over year. The piece also highlights improving profitability and expanding margins, suggesting the stock may still be undervalued despite rising 71% year to date.
Why it matters — SEZL watchers would care because the article frames the recent price decline as a buying opportunity supported by strong subscriber and GMV growth, improving margins, and a favorable valuation relative to peers.